A young professional receives their first salary and wonders where to keep their money. They need easy access for daily expenses like groceries and bills, but they also want to save for future goals. This is where understanding the difference between checkings and savings becomes important. A checking account (often called “checkings” informally) is designed for frequent transactions, while a savings account helps store money securely and earn interest over time.
Many people confuse these two accounts, but knowing the difference between checkings and savings can improve financial decisions. Whether you are a student or a professional, understanding the difference between checkings and savings helps you manage money wisely. In fact, the difference between checkings and savings plays a key role in budgeting, saving, and achieving financial stability.
Key Difference Between Checkings and Savings
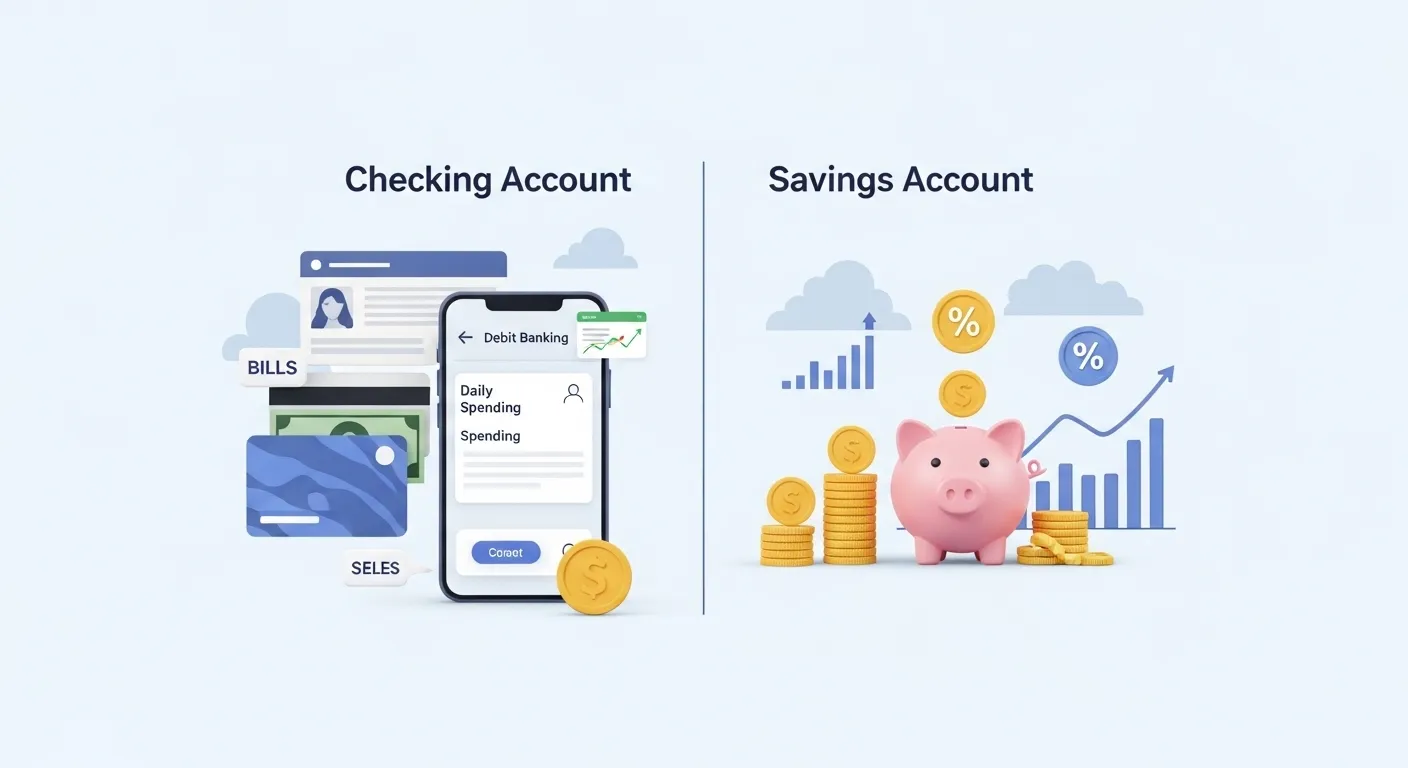
A checking account is used for daily transactions and easy access to money, while a savings account is used to store money and earn interest over time.
Why Is Their Difference Important for Learners and Experts?
For learners, understanding these accounts builds strong financial literacy. For experts, it ensures effective money management and financial planning. In society, checking accounts keep the economy active through daily transactions, while savings accounts promote financial security and future planning. Knowing their difference helps individuals avoid overspending and encourages disciplined saving habits.
Pronunciation
- Checkings (Checking Account)
- US: /ˈtʃekɪŋz/
- UK: /ˈtʃekɪŋz/
- Savings (Savings Account)
- US: /ˈseɪvɪŋz/
- UK: /ˈseɪvɪŋz/
Now, let’s dive deeper into the detailed difference between checkings and savings.
Difference Between Checkings and Savings
1. Purpose
- Checkings: Used for daily spending.
Example 1: Paying utility bills.
Example 2: Buying groceries with a debit card. - Savings: Used for storing money.
Example 1: Saving for a vacation.
Example 2: Building an emergency fund.
2. Accessibility
- Checkings: Easy and frequent access.
Example 1: ATM withdrawals anytime.
Example 2: Online payments. - Savings: Limited access.
Example 1: Withdrawal limits per month.
Example 2: Transfers with restrictions.
3. Interest
- Checkings: Usually little or no interest.
Example 1: Basic checking accounts.
Example 2: Salary accounts. - Savings: Earns interest.
Example 1: Bank savings account interest.
Example 2: High-yield savings accounts.
4. Transactions
- Checkings: Unlimited transactions.
Example 1: Daily purchases.
Example 2: Frequent transfers. - Savings: Limited transactions.
Example 1: Monthly withdrawal limits.
Example 2: Fewer transfers allowed.
5. Fees
- Checkings: May have more fees.
Example 1: Maintenance fees.
Example 2: ATM charges. - Savings: Usually fewer fees.
Example 1: Minimal maintenance fees.
Example 2: No fee for holding money.
6. Minimum Balance
- Checkings: Often low or none.
Example 1: Basic accounts.
Example 2: Student accounts. - Savings: Often requires a balance.
Example 1: Minimum deposit requirement.
Example 2: Penalty for low balance.
7. Risk of Spending
- Checkings: High risk of overspending.
Example 1: Easy card swipes.
Example 2: Frequent withdrawals. - Savings: Low risk of overspending.
Example 1: Withdrawal limits.
Example 2: Less frequent use.
8. Tools and Features
- Checkings: Includes debit cards and checks.
Example 1: Writing checks.
Example 2: Using a debit card. - Savings: Limited tools.
Example 1: Passbook accounts.
Example 2: Online tracking only.
9. Goal
- Checkings: Short-term use.
Example 1: Monthly expenses.
Example 2: Daily transactions. - Savings: Long-term goals.
Example 1: Buying a house.
Example 2: Education fund.
10. Growth
- Checkings: No growth focus.
Example 1: Money stays the same.
Example 2: Used quickly. - Savings: Encourages growth.
Example 1: Interest adds value.
Example 2: Long-term accumulation.
Nature and Behaviour
- Checkings: Active, flexible, and transaction-focused. It is used regularly and supports daily financial activities.
- Savings: Passive, secure, and growth-oriented. It is designed to protect and increase money over time.
Why Are People Confused?
People often confuse these accounts because both are offered by banks and involve storing money. The similar names and overlapping features, such as online access, also create confusion, especially for beginners.
Table: Difference and Similarity
| Aspect | Checkings | Savings | Similarity |
| Purpose | Daily use | Saving money | Both store money |
| Access | High | Limited | Both accessible via banks |
| Interest | Low/None | Higher | Both may earn interest |
| Transactions | Frequent | Limited | Both allow transfers |
| Safety | Secure | Secure | Both are bank-protected |
Which Is Better in What Situation?
A checking account is better for everyday financial activities. It allows easy access to money, making it ideal for paying bills, shopping, and handling daily expenses. If you need flexibility and quick transactions, a checking account is the best choice.
A savings account is better for future planning. It helps you store money safely while earning interest over time. If your goal is to build wealth, save for emergencies, or achieve long-term financial goals, a savings account is the better option.
Metaphors and Similes
- Checkings: “A checking account is like a wallet you use every day.”
- Savings: “A savings account is like a treasure chest for the future.”
Connotative Meanings
- Checkings
- Positive: Convenience, accessibility
Example: Easy access to money - Negative: Overspending
Example: Spending without thinking
- Positive: Convenience, accessibility
- Savings
- Positive: Security, discipline
Example: Building financial stability - Neutral: Reserved funds
Example: Money set aside
- Positive: Security, discipline
Idioms and Proverbs
- “Save for a rainy day”
Example: Always save for a rainy day using a savings account. - “Live paycheck to paycheck”
Example: Without savings, people may live paycheck to paycheck using only checking accounts.
Works in Literature
- The Richest Man in Babylon Finance, George S. Clason, 1926
- Your Money or Your Life Personal Finance, Vicki Robin & Joe Dominguez, 1992
Movies Related to Finance
- The Pursuit of Happyness 2006, USA
- The Big Short 2015, USA
FAQs
1. Can I have both accounts?
Yes, most people use both for better money management.
2. Which account earns more interest?
Savings accounts usually earn more interest.
3. Is checking safer than savings?
Both are equally secure in banks.
4. Can I transfer money between them?
Yes, transfers are usually easy and quick.
5. Which is better for daily use?
Checking accounts are better for daily transactions.
How Both Are Useful for Surroundings
Checking accounts keep daily financial activities smooth and efficient, while savings accounts promote stability and future planning. Together, they support individuals, families, and the economy by balancing spending and saving habits.
1. How the Checking Account Drives Local Economic Velocity
A checking account is the financial engine of daily life. Its primary utility to the surrounding environment is the speed and efficiency of transactions, often referred to in economics as the velocity of money.
- Sustaining Local Commerce: Every time an individual swipes a debit card or sends an electronic transfer from a checking account, cash instantly flows into a local business’s coffers. This immediate liquidity allows small businesses to restock inventory, pay utilities, and keep their doors open.
- Employment and Wage Stability: Modern businesses rely on automated payroll systems. By utilizing checking accounts, workers receive direct deposits smoothly and reliably. This predictable income flow means families can pay rent, buy groceries, and purchase services on a dependable schedule, preventing sudden drops in local consumer spending.
- Infrastructure and Public Services: Checking accounts are the primary conduit for paying utility bills, transit fares, and local property or sales taxes. This consistent digital flow of funds ensures that city infrastructure like public schools, road maintenance, and emergency services remains funded and operational.
2. How the Savings Account Fuels Community Development
While checking accounts keep money moving, savings accounts pool money together. In a healthy economy, a savings account is not just cash sitting passively in a vault; it serves as a critical asset for community lending.
- The Fractional Reserve System: When individuals deposit money into savings accounts, banks don’t just hold it. They are legally permitted to lend out a significant portion of those pooled deposits to other members of the community.
- Funding Entrepreneurship and Innovation: The capital sitting in local savings accounts directly funds commercial loans for small business owners who want to open a storefront, purchase equipment, or hire more staff from the neighborhood.
- Enabling Homeownership: Mortgages are heavily supported by the stable pool of long-term deposits held in savings accounts. When a community saves collectively, it increases the local bank’s capacity to issue home loans, helping families build generational wealth and stabilizing the local real estate market.
3. The Mutual Defense Against Economic Fragility
When families balance both accounts, they create a safety net that protects the broader society from economic shocks.
[ Individual Emergency Fund ] ──> Less Reliance on Public Assistance
              │
              ▼
[ Stable Local Communities ]  ──> Fewer Loan Defaults & Foreclosures
              │
              ▼
[ Resilient National Economy ] ──> Continuous, Steady Market Growth
- Reducing the Burden on Social Safety Nets: When an unexpected crisis hits such as a medical emergency or sudden job loss a checking account is usually empty within weeks. A robust savings account acts as a personal buffer, reducing the immediate, systemic strain on government welfare programs, food banks, and community charities.
- Preventing Debt Cascades: Without savings, individuals facing an emergency often resort to predatory payday loans or high-interest credit card debt. This drain on personal income means less money is spent at local businesses. A healthy savings culture keeps consumer purchasing power alive, even during minor recessions.
Final Words for Both
Checking accounts manage your present, while savings accounts protect your future. Both are essential tools for a balanced financial life.
Conclusion
Understanding the difference between checkings and savings is essential for effective financial management. Checking accounts provide easy access for daily expenses, while savings accounts help build financial security over time. Both serve unique purposes and complement each other in managing money wisely. By using them correctly, individuals can achieve financial stability and long-term success. Whether you are starting your financial journey or improving your skills, knowing their difference ensures smarter decisions and a better future.
I am a professional SEO content writer specialising in comparison-based and grammar-focused articles. Through my website GrammarCompare.com, I help readers clearly understand the difference between confusing terms with well-researched, easy-to-read content. My expertise lies in focusing on clarity, accuracy, and practical explanations that improve both knowledge and writing skills.