Every adult faces a crucial life decision when moving into a home: should they choose a mortgage or rent? Imagine a young professional moving to a new city for work. He stands in front of two options buying a house through a loan or renting an apartment. This is where the difference between mortgage and rent becomes important. Many people discuss the difference between mortgage and rent when planning their financial future, yet still feel confused. The difference between mortgage and rent affects long-term wealth, flexibility, and financial responsibility. Understanding the difference between mortgage and rent helps individuals make smarter housing choices and avoid financial mistakes in real life.
Key Difference Between the Both
A mortgage is a loan used to buy property, while rent is a payment made to live in someone else’s property.
Why Their Difference Matters
Knowing the difference between mortgage and rent is essential for families, investors, and professionals because housing decisions directly impact economic stability and lifestyle choices in society.
Pronunciation
- Mortgage
US: /ˈmɔːrɡɪdʒ/
UK: /ˈmɔːɡɪdʒ/ - Rent
US: /rent/
UK: /rent/
Now let’s explore the difference between mortgage and rent in detail.
H2: Difference Between Mortgage and Rent
1. Ownership
- Mortgage: Leads to ownership of property
Examples: Buying a house, owning land after loan repayment - Rent: No ownership rights
Examples: Living in a rented apartment, paying landlord monthly
2. Payment Nature
- Mortgage payments build equity.
Examples: Monthly home loan installment, property investment - Rent payments are expenses only.
Examples: Monthly rent for flat, lease payment
3. Long-term Value
- Mortgage builds long-term asset value.
Examples: House appreciation, property resale profit - Rent provides no asset value.
Examples: Temporary housing, short-term stay
4. Financial Commitment
- Mortgage is long-term (15–30 years).
Examples: Bank home loan, EMI system - Rent is short-term (monthly/yearly).
Examples: Lease agreement, flexible contract
5. Maintenance Responsibility
- Mortgage owners handle maintenance.
Examples: Roof repair, plumbing costs - Renters usually rely on landlords.
Examples: Repair requests, building maintenance
6. Flexibility
- Mortgage offers low flexibility.
Examples: Hard to relocate, long contracts - Rent offers high flexibility.
Examples: Easy relocation, job-based moving
7. Initial Cost
- Mortgage requires down payment.
Examples: 10–20% property value upfront - Rent requires deposit only.
Examples: One-month security deposit
8. Risk Factor
- Mortgage carries financial risk.
Examples: Loan default, property market crash - Rent carries low financial risk.
Examples: No long-term debt burden
9. Tax Benefits
- Mortgage may offer tax deductions.
Examples: Interest deduction, property tax benefits - Rent rarely offers tax advantages.
Examples: Minimal or no deductions
10. Emotional Security
- Mortgage provides stability and pride.
Examples: Family home ownership, permanent residence - Rent provides temporary comfort.
Examples: Short-term living comfort, shared housing
Nature and Behavior
Mortgage behaves like a long-term financial investment. It grows in value, requires responsibility, and builds ownership over time.
Rent behaves like a flexible service. It offers temporary shelter without long-term commitment or ownership pressure.
Why People Get Confused
People confuse mortgage and rent because both involve monthly payments for housing. Also, in early stages, mortgage payments feel similar to rent. Marketing from banks and real estate agents often blurs the distinction, making the difference between mortgage and rent unclear.
Table: Difference and Similarity
| Feature | Mortgage | Rent |
| Ownership | Yes | No |
| Purpose | Buying property | Using property |
| Duration | Long-term | Short-term |
| Asset building | Yes | No |
| Flexibility | Low | High |
Similarity: Both require regular payments and provide housing solutions.
Which is Better in What Situation?
A mortgage is better when a person has stable income, long-term settlement plans, and wants to build wealth through property ownership. It is ideal for families planning permanent residence and financial investment.
Rent is better for students, job changers, and individuals who need flexibility. It suits people who are not ready for long-term financial commitment. Renting also helps those exploring new cities or saving for future property purchase. In short, mortgage suits stability and investment goals, while rent suits flexibility and temporary living needs.
Metaphors and Similes
- Mortgage is like planting a tree that grows into long-term shelter.
- Rent is like staying in a hotel comfortable but temporary.
Example:
- His mortgage was like a foundation stone for his future.
- Her rented apartment was as flexible as a traveling tent.
Connotative Meaning
- Mortgage: Positive (security, ownership, investment)
Example: “A mortgage gave them a permanent home.” - Rent: Neutral to positive (flexibility, access, convenience)
Example: “Rent allowed him to move freely for work.”
Idioms or Proverbs
- “Home is where the mortgage builds your future.”
Example: He believes home is where the mortgage builds your future. - “Rent is freedom without ownership chains.”
Example: For students, rent is freedom without ownership chains.
Works in Literature
- Home Ownership and Society – Non-fiction, David Clark, 2015
- The Rent Generation – Sociology study, Anna Brooks, 2019
- Building Wealth Through Property – Finance guide, Robert King, 2021
Movies
- The Mortgage Dream (2018, USA)
- Rent Life (2020, UK)
- Home vs Freedom (2022, Canada)
Frequently Asked Questions
1. Is mortgage better than rent?
It depends on financial stability and long-term goals.
2. Can rent turn into ownership?
Not usually, unless there is a rent-to-own agreement.
3. Why is mortgage more expensive?
It includes loan interest and long-term commitment.
4. Is renting waste of money?
No, it offers flexibility and short-term housing.
5. What is safer financially?
Rent is safer in the short term; mortgage builds long-term wealth.
How Both Are Useful for Surroundings
Mortgages support the real estate economy and long-term urban development, while renting supports mobility, urban flexibility, and housing accessibility for diverse populations.
Final Words
Both mortgage and rent play important roles in modern housing systems. One builds ownership and long-term financial security, while the other provides flexibility and short-term comfort. Understanding both helps individuals make smarter housing decisions based on their personal and financial situations.
Conclusion (100–150 words)
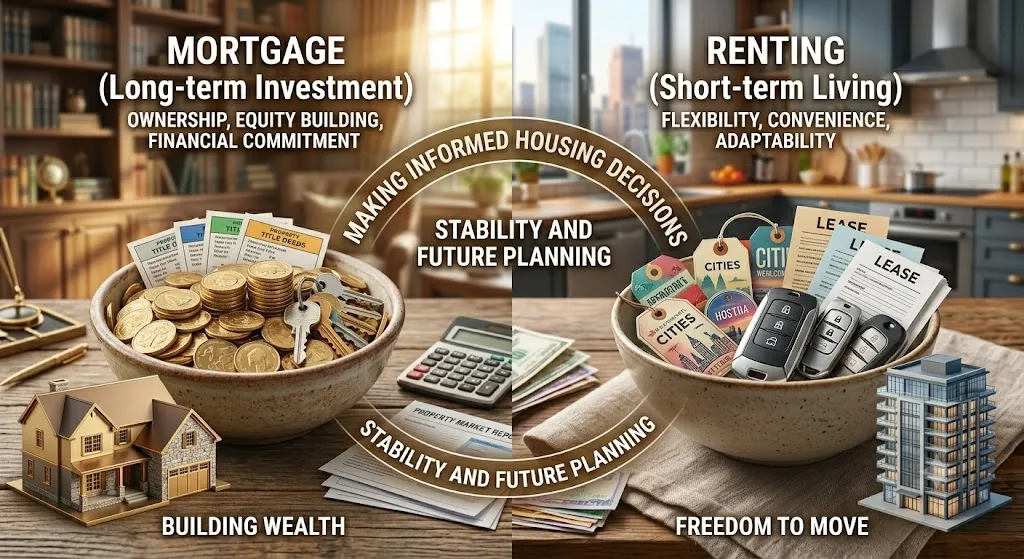
Understanding the difference between mortgage and rent is essential for making informed housing decisions. A mortgage represents long-term investment, ownership, and financial commitment, while rent represents flexibility, convenience, and short-term living. The difference between mortgage and rent helps individuals choose the right path based on their income, lifestyle, and future plans. For some, owning a home through a mortgage is a step toward stability and wealth building. For others, renting provides freedom to move and adapt without financial pressure. Knowing the difference between mortgage and rent reduces confusion and supports better financial planning in real life. Ultimately, both options serve important roles in society, offering solutions for different needs and life stages. To help visualize this decision for a financial planning guide, infographic, or blog post, here is a clear breakdown of how these two housing paths function in real life.
Mortgage vs. Rent: The Core Distinction
| Feature | Mortgage (Homeownership) | Renting (Leasing) |
| Financial Nature | An investment that builds equity over time. | An expense paid monthly for immediate shelter. |
| Asset Ownership | You own the property (jointly with the lender until paid off). | The landlord owns the property; you own no equity. |
| Flexibility | Low. Selling a home takes time, effort, and transaction costs. | High. You can relocate easily once your lease ends. |
| Maintenance | Your responsibility. You pay for repairs, updates, and upkeep. | Landlord’s responsibility. Maintenance is covered by rent. |
The Spectrum of Choice: Key Factors
Choosing the right path depends entirely on evaluating three pillars: your current financial health, your career trajectory, and your personal lifestyle goals.
1. Wealth Building vs. Sunk Costs
- The Mortgage Path: Every monthly payment is divided into interest (the cost of borrowing) and principal. The principal portion reduces your loan balance, effectively acting as a “forced savings account” that builds home equity. Over decades, property appreciation can significantly increase your net worth.
- The Renting Path: Your monthly payment is a pure consumption cost. While you never see that money again, renting frees up capital that would otherwise be locked in a down payment, allowing you to invest it elsewhere (like the stock market or a business).
2. Stability vs. Freedom to Adapt
- The Mortgage Path: It offers unmatched predictability. If you secure a fixed-rate mortgage, your core housing payment stays the same for 15 to 30 years, protecting you from rising housing market costs. This creates a deeply rooted foundation for families and long-term community ties.
- The Renting Path: It gives you the ultimate freedom to adapt. If you get a job offer in another city, experience an income shift, or simply want a change of scenery, you can move at the end of your lease without the complex burden of selling a piece of real estate.
A Quick Tip on Hidden Costs: When comparing a monthly mortgage payment to monthly rent, remember to factor in the “unrecoverable costs” of homeownership. Property taxes, homeowners insurance, and HOA fees can add hundreds of dollars to a monthly budget that do not go toward building equity.
I am a professional SEO content writer specialising in comparison-based and grammar-focused articles. Through my website GrammarCompare.com, I help readers clearly understand the difference between confusing terms with well-researched, easy-to-read content. My expertise lies in focusing on clarity, accuracy, and practical explanations that improve both knowledge and writing skills.