A few years ago, Ali needed to send money to his friend living abroad after splitting a freelance project payment. He opened PayPal to make an international transfer, but later, when paying a local friend for dinner, he noticed everyone preferred Venmo. This simple experience highlights the difference between PayPal and Venmo in everyday life. While both are digital payment platforms, the difference between PayPal and Venmo lies in their purpose, audience, and features. Many people often confuse them, but understanding the difference between PayPal and Venmo can save time, fees, and effort. Whether you are a beginner or an expert, knowing the difference between PayPal and Venmo helps you choose the right tool for personal or professional transactions.
Key Difference Between the Both
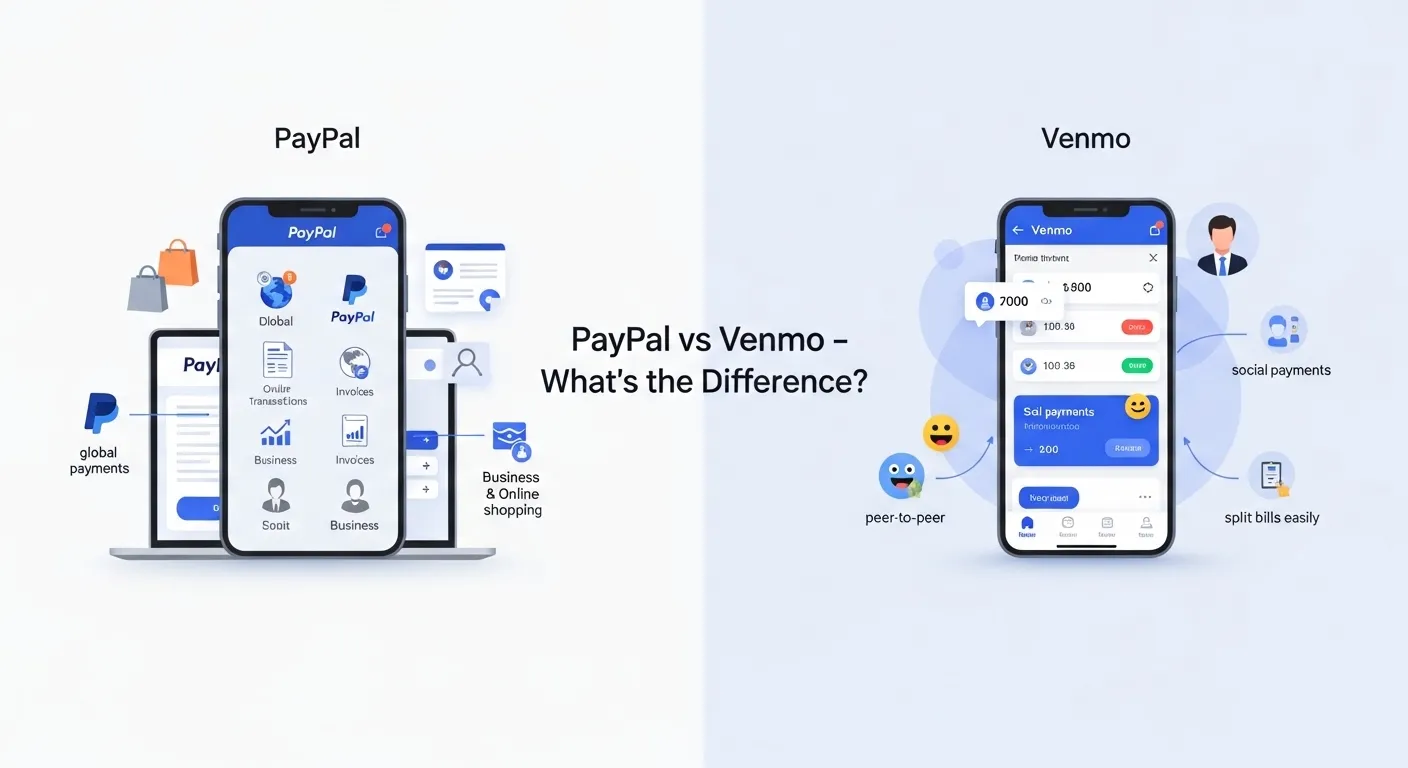
The main difference is that PayPal is designed for global and business transactions, while Venmo is focused on social, peer-to-peer payments within the United States.
Why Their Difference Is Necessary to Know
Understanding the difference is important for learners and experts because it affects financial decisions, security, and convenience. Businesses rely on PayPal for international payments, while individuals use Venmo for quick social transactions. In society, these platforms support digital economies, freelancing, and cashless interactions.
Pronunciation
- PayPal:
- US: /ˈpeɪ.pæl/
- UK: /ˈpeɪ.pæl/
- Venmo:
- US: /ˈven.moʊ/
- UK: /ˈven.məʊ/
Now that you understand the basics, let’s explore the detailed comparison.
Difference Between PayPal and Venmo
1. Purpose
PayPal is used for business and international payments.
Example 1: A freelancer receives money from another country.
Example 2: An online store accepts PayPal payments.
Venmo is used for social and personal transfers.
Example 1: Friends split a dinner bill.
Example 2: Roommates share rent payments.
2. Geographic Availability
PayPal works worldwide.
Example 1: Sending money from Pakistan to the USA.
Example 2: Buying products from international websites.
Venmo works mainly in the USA.
Example 1: Paying a friend in New York.
Example 2: Sending money locally in California.
3. Audience
PayPal targets businesses and professionals.
Example 1: E-commerce websites.
Example 2: Freelancers and companies.
Venmo targets individuals.
Example 1: Students sharing expenses.
Example 2: Friends paying each other.
4. Social Features
PayPal has limited social features.
Example 1: Simple transaction records.
Example 2: No social feed.
Venmo includes a social feed.
Example 1: Users can like payments.
Example 2: Emojis in transactions.
5. Fees
PayPal charges fees for many services.
Example 1: International transfer fees.
Example 2: Business transaction fees.
Venmo has fewer fees for personal use.
Example 1: Free bank transfers.
Example 2: Charges only for instant transfers.
6. Security
PayPal offers strong buyer protection.
Example 1: Refund for faulty products.
Example 2: Fraud protection in purchases.
Venmo has limited protection.
Example 1: Less support for disputes.
Example 2: Mostly for trusted contacts.
7. Business Use
PayPal supports business accounts.
Example 1: Accepting customer payments.
Example 2: Sending invoices.
Venmo has limited business use.
Example 1: Small vendors.
Example 2: Informal transactions.
8. Payment Methods
PayPal supports many methods.
Example 1: Credit cards.
Example 2: Bank accounts.
Venmo supports fewer options.
Example 1: Linked bank account.
Example 2: Debit card.
9. International Transactions
PayPal allows global transfers.
Example 1: Paying overseas clients.
Example 2: Buying from foreign stores.
Venmo does not support international payments.
Example 1: Cannot send abroad.
Example 2: Limited to domestic use.
10. Professional Features
PayPal offers advanced tools.
Example 1: Subscription billing.
Example 2: Payment gateways.
Venmo offers basic features.
Example 1: Simple transfers.
Example 2: Social interaction focus.
Nature and Behaviour
PayPal is formal, secure, and business-oriented. It focuses on reliability and global reach.
Venmo is casual, social, and user-friendly. It focuses on ease and interaction among friends.
Why People Are Confused
People confuse them because both are owned by the same parent company (historically) and perform similar functions. Their mobile apps and interfaces look alike, and both allow digital money transfers.
Table: Difference and Similarity
| Feature | PayPal | Venmo | Similarity |
| Purpose | Business & global | Personal & social | Both transfer money |
| Availability | Worldwide | USA only | Digital platforms |
| Fees | Higher | Lower | Some charges apply |
| Security | Strong | Moderate | Both secure |
| Social Features | No | Yes | Mobile apps |
| Users | Businesses | Individuals | Online wallets |
Which Is Better in What Situation?
PayPal is better for professional and international use. If you run a business, work as a freelancer, or shop globally, PayPal provides strong security and flexibility. It supports multiple currencies and protects buyers and sellers.
Venmo is better for personal and social use. If you want to quickly send money to friends or split bills, Venmo is simple and fun. Its social features make transactions engaging and easy to track among contacts.
Metaphors and Similes
- PayPal is like a bank manager formal and reliable.
- Venmo is like a friendly cashier quick and social.
Connotative Meaning
- PayPal: Positive (professional, secure)
- Example: “Use PayPal for safe business deals.”
- Venmo: Neutral to positive (casual, social)
- Example: “Send it on Venmo, it’s quick.”
Idioms or Proverbs
(No direct idioms exist, but related usage examples)
- “Money talks” PayPal is used where money matters seriously.
- “Easy come, easy go” Venmo reflects quick and easy transfers.
Works in Literature
- Digital Payments Revolution Non-fiction, John Smith, 2020
- Cashless Society – Economics, Jane Doe, 2018
Movies Related to Digital Payments
- The Social Network (2010, USA)
- Startup.com (2001, USA)
FAQs
1. Is PayPal safer than Venmo?
Yes, PayPal offers stronger buyer protection and security features.
2. Can Venmo be used internationally?
No, Venmo is limited to the USA.
3. Which is better for business?
PayPal is better for business transactions.
4. Is Venmo free to use?
Yes, mostly free for standard transfers.
5. Can I use both?
Yes, many people use PayPal for business and Venmo for personal use.
How Both Are Useful for Surroundings
Both platforms support a cashless society. They reduce the need for physical money, improve transaction speed, and support digital businesses and personal convenience.
Final Words
PayPal stands as a global, professional payment solution, while Venmo shines as a simple and social money sharing app. Both serve unique roles in modern finance.
Conclusion
In conclusion, understanding the difference between PayPal and Venmo is essential in today’s digital world. While both platforms enable easy money transfers, they serve different purposes. PayPal is ideal for businesses, international transactions, and secure payments, whereas Venmo is perfect for quick, personal exchanges among friends. Choosing the right platform depends on your needs, whether professional or casual. By learning their differences, users can make smarter financial decisions and enjoy the convenience of digital payments efficiently.
1. The Core Mechanical Divide: Formal Commerce vs. Peer-to-Peer (P2P)
The foundational difference lies in the types of transactions each platform was built to facilitate.
PayPal: The Global Financial Vault
PayPal functions as a robust digital bank replacement for global commerce. It is designed to act as a secure intermediary between buyers, sellers, and traditional financial institutions.
- The Architecture: It relies heavily on email addresses or specific merchant integration buttons at checkout.
- The Safety Net: It features PayPal Buyer Protection. If you purchase an item online and the seller scams you, PayPal will investigate and refund your money. This makes it the industry standard for freelance invoicing, e-commerce stores, and high-value transactions.
Venmo: The Digital Cash Wallet
Venmo was built to digitalize the act of handing a friend a $20 bill. It is explicitly optimized for fast, low-stakes peer-to-peer exchanges.
- The Architecture: It relies on a mobile-first app layout using phone numbers, usernames, or scannable QR codes.
- The Safety Net: Standard Venmo transactions offer zero buyer protection. If you accidentally send $500 to the wrong username, or use Venmo to buy a laptop from a stranger on the street, Venmo will not refund your money if the transaction goes wrong.
2. Fee Traps and Regulatory Pitfalls
Because Venmo has grown rapidly, many casual users mistakenly use it for business purposes, which can lead to costly penalties:
- The “Goods and Services” Toggle: Venmo recently introduced a “Turn on for purchases” toggle. If you are buying an item from someone you don’t know, turning this on charges the seller a 1.9% + $0.10 fee but gives you buyer protection. If you use standard personal Venmo to run a side business without declaring it, Venmo’s algorithms may freeze your account for violating their terms of service.
- Instant Transfer Monopolies: Both platforms allow you to transfer your digital balance to your bank account for free via a standard 1-to-3 day ACH transfer. However, if you need the cash immediately, both charge a 1.75% fee (with varying minimums and maximum caps) for an instant transfer to your debit card.
I am a professional SEO content writer specialising in comparison-based and grammar-focused articles. Through my website GrammarCompare.com, I help readers clearly understand the difference between confusing terms with well-researched, easy-to-read content. My expertise lies in focusing on clarity, accuracy, and practical explanations that improve both knowledge and writing skills.